Whose Deal Is It Anyway?

Terri Stallworth • 2 November 2026

Some of the hardest deals I work on are not the ones where the buyer and seller disagree. They are the ones where the buyer and seller get along well, trust each other, and want the same outcome, yet still watch the closing date slide a little further away every week.


Picture a deal like this one: A seller has spent years building a business and has found a buyer she genuinely likes. The buyer has done his homework and believes in what she built. The price is agreed, the lender is engaged, and the two of them have already had good conversations about the transition. On paper, this is the deal everyone hopes for. Somehow, though, emails go unanswered, documents that should take days take weeks, and every call (or email) seems to surface a new concern that neither the buyer nor the seller actually raised.

When that happens, the problem usually isn’t between the two people at the center of the deal, but instead it’s somewhere in the circle of people around them.


Where the Friction Comes From


Every buyer and seller brings a team to the table, whether that’s a broker, an attorney, a CPA, or a trusted advisor they’ve worked with for years. Most of the time, that team is the reason a deal gets done. There are times, though, I’ve seen friction come from inside the deal team in a few different ways. Sometimes an advisor doesn’t have much experience with a particular deal structure and moves cautiously because it’s unfamiliar. Sometimes it’s responsiveness, where a capable person is stretched across too many files and yours keeps sliding to the bottom of the pile. Sometimes, if we’re being honest, an advisor is more focused on protecting their own position in the deal than on helping their client reach the finish line.


What I notice most is what buyers and sellers do with their frustration. They vent, and they usually vent to whoever is closest and safest to talk to, which tends to be their broker, their spouse, or another member of their own team. It’s a completely human response. The trouble is that the person hearing the frustration is rarely the person causing the delay, so the conversation may release a little pressure but it rarely changes anything about the actual deal issues.


When It’s More Than a Slow Week


Not every delay is a problem. Deals have natural pauses, people take vacations, and some questions or requests genuinely take time to answer. The signals I pay attention to are more specific. The first is a pattern of unanswered calls, emails, or outreach, where the follow-ups start to outnumber the replies. The second is a deliverable that keeps slipping, where something everyone is waiting on gets pushed back again and again without a clear reason.


How much delay is too much depends on where the deal is in its timeline. A few quiet days early in the process may not matter much. Those same few days can matter a great deal when the delay touches something time-sensitive, like a document the lender is waiting on, a conversation with the landlord that needs to wrap up before closing, or a closing date that depends on one person finishing their part. That is usually the point where a slow week becomes a real risk to the deal.


One Phone Call That Changed the Outcome


A while back, I represented a buyer whose attorney was working outside his usual practice. I’m not suggesting he was a bad attorney, but it became obvious that the type of transaction structure needed wasn’t within his scope, and the deal slowed down around him. Messages went unreturned, he was absent from some important conversations, and items we needed sat much longer than they should have.


For several weeks, my buyer lightly vented to me about it. I understood his frustration, and at one point I reminded him that he was the attorney’s client. He was paying for a service, and he had every reason to expect that he was getting what he was paying for.


He decided on his own to call the firm. He didn’t argue about the work or try to tell anyone how to do their job. He simply explained that he was frustrated, that he was on a timeline, and that he needed someone who could help him get the deal done. The firm listened and moved him to another attorney who was responsive and fully engaged, and we got the deal closed.


I give that firm a lot of credit, because they handled it well, but it was my buyer’s direct conversation that moved the needle. Several weeks of venting hadn’t changed anything, and one clear phone call from the client did.


Why Your Voice Carries More Weight

When I sense a breakdown somewhere on the deal team, my first step is usually to reach out myself or try to nudge things along. Sometimes that’s all it takes. When it isn’t, I encourage my buyer or seller to reach out directly because the request lands differently when it comes from the person the advisor actually works for. A follow-up from another advisor is easy to set aside for another day, but a clear request from the client is much harder to ignore.


Timing matters too. In my buyer’s case, waiting a while to reach out to the firm made sense because the deal still had real momentum, but that changes once the delay reaches the time-sensitive elements of the deal.


The conversation itself can take two shapes. Often it’s a reset, where you let your advisor know what you need and what your timeline is, and ask them to help you get there. Occasionally, as with my buyer, it means asking for someone else to handle the work. You’ll usually know which one you need by how that first conversation goes. Either way, it works best when it sounds the way my buyer’s call did, focused on your situation, your timeline, and getting the deal done.


The Question I Ask Myself


I’m part of the deal team too, so I want to be fair about this. Every advisor, me included, can slip into protecting their own position instead of serving the deal. The question I try to keep asking myself is a simple one: Am I helping right now, or am I protecting my position?


It’s a useful question for you to keep in mind as well because you can often see the answer from the outside. An advisor who is helping keeps bringing the conversation back to your goals and your timeline. One way I try to do that is by putting the buyer and seller in direct conversation as often as I can, even when the advisors are on the call too, so the two people who built the trust in the deal stay at the center of it. An advisor who is protecting their position tends to pull the deal toward themselves instead, and over time you can usually feel the difference.


It’s Your Deal


You brought your broker, attorney, and CPA onto your team to help you reach a goal, and the best of them are glad to hear from you when something isn’t working. If your deal is stalling and the frustration keeps coming out in conversations that don’t change anything, it may be time to have the one conversation that can. It’s your deal, and you’re the client. Always remember that.
by Terri Stallworth • 16 July 2026
July is here, which means summer is in full swing and the year is already more than halfway over. For small business owners, this is actually one of the most important moments on the financial calendar. The decisions you make right now about how you manage your money can make or break your Q3 and Q4. Here's how QuickBooks can help you finish the year strong: 1. Get a real-time snapshot of where you stand Before you can plan ahead, you need to know where you are. QuickBooks' built-in reporting lets you pull a mid-year profit & loss report in seconds — no accountant needed. See exactly what came in, what went out, and where there's room to tighten up before the back half of the year kicks off. 2. Stop chasing invoices during your busiest season Summer is the peak season for a lot of small businesses — more projects, more clients, more moving parts. QuickBooks lets you send professional invoices, set up automatic payment reminders, and track outstanding balances all in one place. So you get paid on time, even when things get hectic. 3. Keep your books clean now, so tax time isn't a nightmare later Here's the thing nobody talks about in July: the habits you build right now will determine how stressful tax season is. QuickBooks automatically categorizes transactions, syncs with your bank accounts, and keeps a running record of your income and expenses. A little organization now saves a lot of headaches in April. The second half of 2026 is yours. Start it with a clear picture of your finances. 👉 Get started with QuickBooks here .
by Terri Stallworth • 15 June 2026
If I could give every seller just one piece of advice in preparing for a listing meeting, it would be this: be open and honest about the not-so-pretty parts of your business right out of the gate. I know that may sound counterintuitive. The instinct for most sellers is to lead with strengths and hope the warts stay hidden. But here's the reality: the warts are coming out either way. The only real question is whether you bring them up first, framed by you, with context and a plan attached, or whether the buyer's diligence team finds them six weeks in, with no framing and no opportunity to recover credibility. If I’ve ever talked with you personally about this, you’ve most likely heard me say, "The goal is to play offense, not defense.” When you play offense in your role of the transaction, three things happen: You build immediate credibility with the buyer. Sellers who acknowledge weaknesses early are trusted far more on every claim that follows. You shift the conversation from what's wrong to where's the opportunity . The same fact, surfaced by you with thoughtful framing, becomes a launching pad for value rather than a deal-killer. You give yourself room to polish. Some issues can be cleaned up before you go to market, but you can only do that work if the issue has been named out loud. Buyers are often looking for reasons not to buy. There's no need to help them find any. The strongest sellers I've worked with treat disclosure not as a defensive obligation but as a strategic tool, and that difference shows up at every stage of the deal.
by Terri Stallworth • 12 June 2026
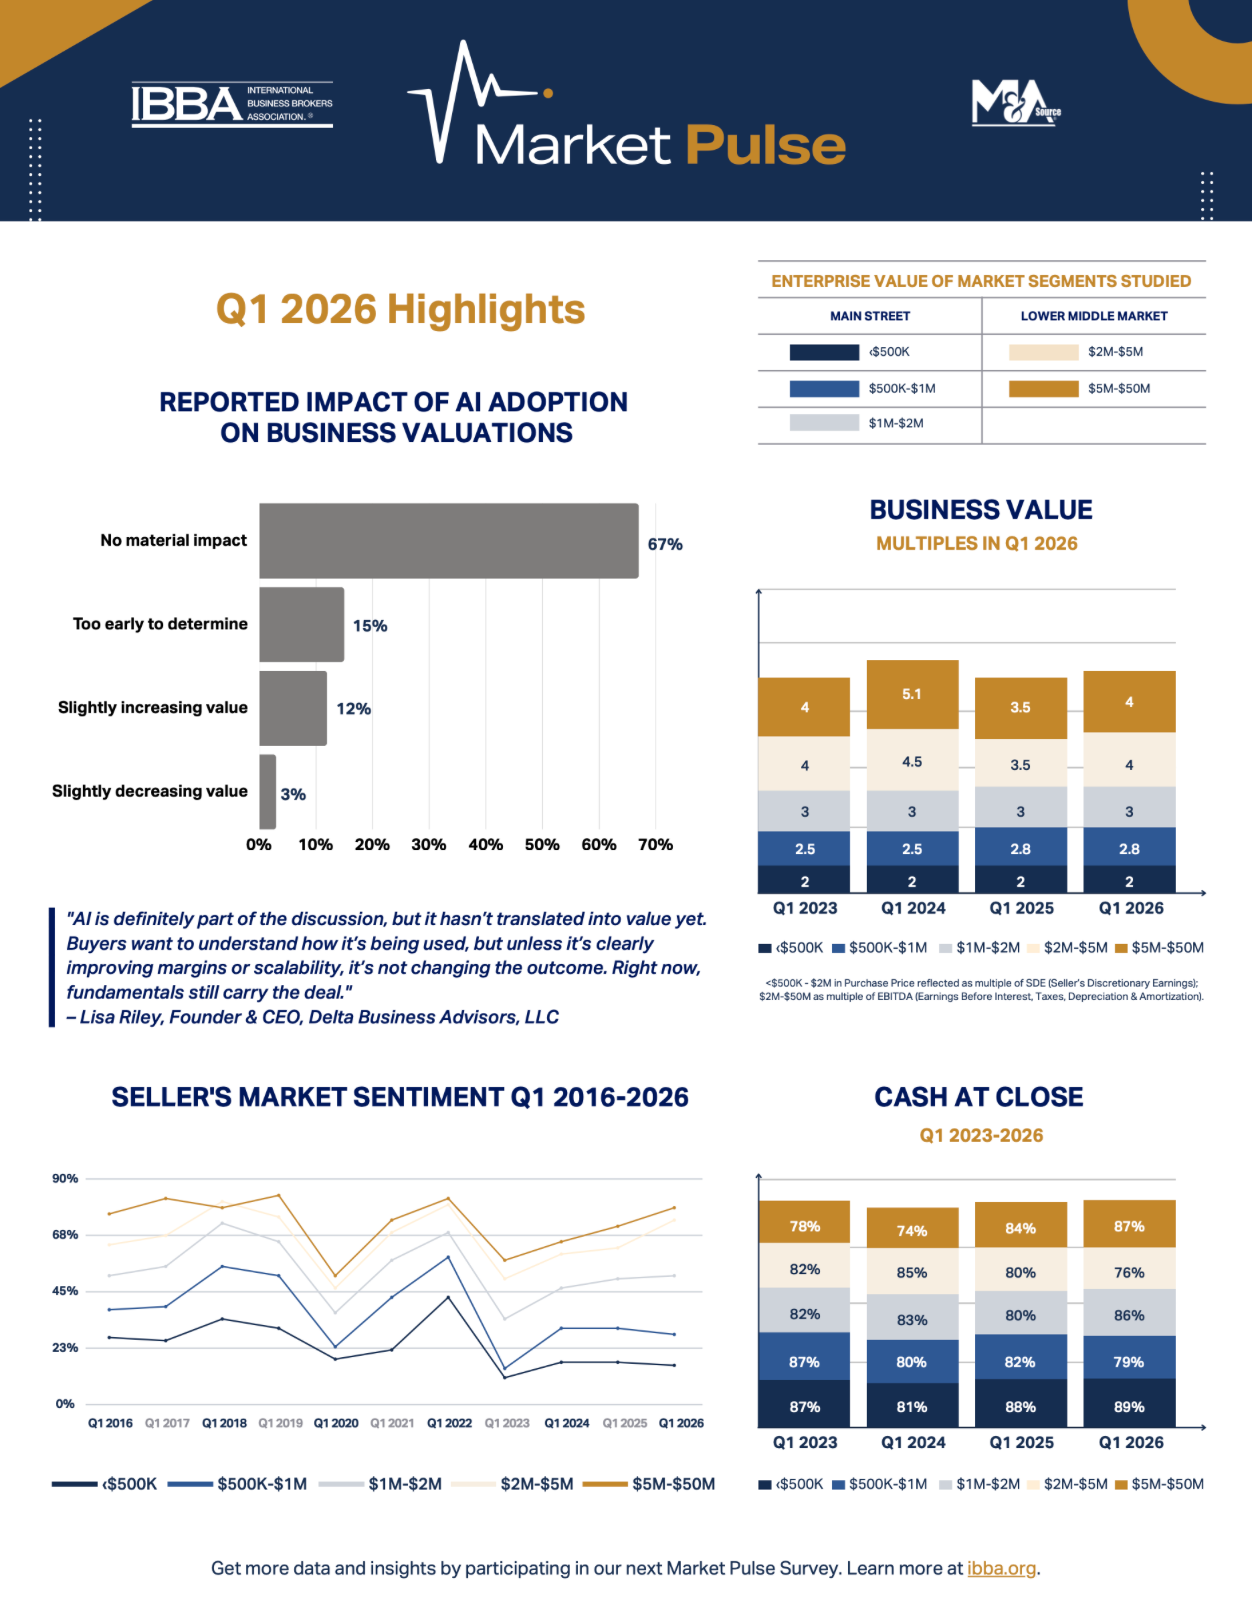
Half. That’s the headline number from the just-released Q1 2026 Market Pulse survey*, the quarterly survey of business brokers and M&A advisors nationwide. This quarter’s report surveyed 300 respondents. Fifty percent of the transactions reported in the quarter by those respondents terminated without closing, up slightly from 48% in Q1 2025. That number is striking on its own. It’s more striking against the rest of the data, which describes a market that is active and functioning. Forty-three percent of advisors reported stronger transaction activity over the last twelve months, against just 21% reporting weaker conditions. Seller confidence is climbing back toward prior peaks, particularly in the lower middle market. Multiples and cash-at-close levels are holding steady. And sellers are receiving between 84% and 98% of their benchmark price for businesses valued up to $5 million, with the strongest performance at the larger end of that range. So the market isn’t the problem. Buyers are showing up, money is moving, and yet one in two deals is dying somewhere between handshake and close. To understand why, it helps to look at who’s at the table and how they’re paying for it. In Q1 2026, the most common buyer for a business valued up to $5 million was a first-time buyer, and their leading motivation was to buy themselves a job. These are people leaving a paycheck to take over a business, and they overwhelmingly depend on financing to reach the closing table. That shows up clearly in how deals got paid for. Across these same segments, cash at close ranged from 76% to 89%, with seller financing making up another 10% to 16% of most deals. Even in the most cash-heavy segment, better than one dollar in ten came from somewhere other than the buyer’s own cash and senior debt. The lesson for sellers starts here. In this market, financing is part of nearly every transaction. If you’re listing your business expecting an all-cash buyer to walk in and write a check, the data says reset that expectation. Once financing is involved, so is a lender, and a lender potentially means increased scrutiny. That’s where the second half of the data is telling because the people walking into that scrutiny are, by and large, walking in for the first time. Eighty-six percent of advisors report that first-time sellers make up at least half of their current engagements, and 60% say first-timers account for three-quarters or more. Most of them arrive unprepared, according to the survey, unfortunately. Across the segments up to $5 million, between 39% and 68% of sellers engaged in no formal planning at all before going to market, and the smaller the business, the more pronounced the gap. As Scott Bushkie of Cornerstone Business Services observed in the report, many owners are navigating one of the most significant financial events of their lives with no prior experience to draw on. When you haven’t done it before, he noted, “you don’t know what you don’t know.” So here is the picture Q1 2026 actually paints: an active market, full of first-time sellers who haven’t prepared, meeting first-time buyers who can’t close without a lender’s approval. That combination is exactly where deals die. The next section walks through a real example of one of them. Source: IBBA & M&A Source Market Pulse Survey, Q1 2026. *If you would like a courtesy copy of the full report, message me here to request a copy.
by Terri Stallworth • 10 June 2026
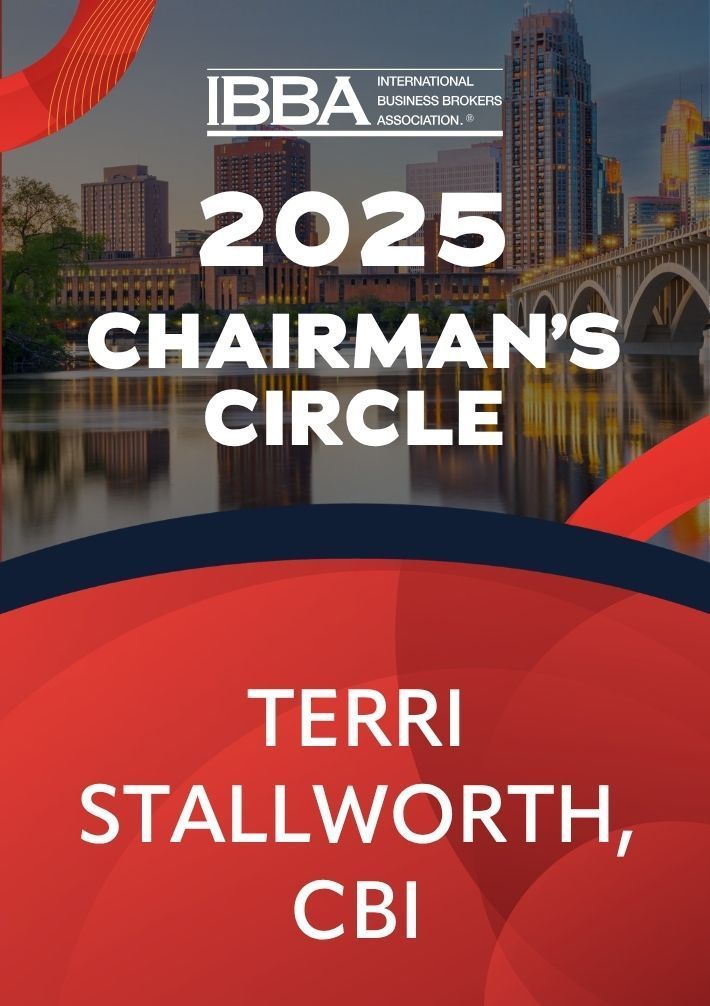
FOR IMMEDIATE RELEASE Terri Stallworth Recognized by the International Business Brokers Association with 2025 Chairman’s Circle Award Jacksonville, FL – June 10, 2026 – Terri Stallworth, Certified Business Intermediary of Florida Business Exchange, Inc. (FBX) has been recognized by the International Business Brokers Association (IBBA) with the prestigious Chairman’s Circle Award for outstanding performance during 2025. The award was presented at the 2026 IBBA Annual Conference held in Minneapolis, Minnesota. The IBBA is the world's largest professional trade association for Business Brokers and M&A Advisors. The Chairman’s Circle Award recognizes business brokerage professionals who have demonstrated exceptional achievement in facilitating successful business transactions and serving business owners throughout the business transfer process. “This award is a great honor because it speaks to the education and training that I have benefitted from over the years through the IBBA, Business Brokers of Florida, and FBX, but more than that, it speaks to all of the business owners, customers, referral partners, and supporters who have put their trust in me to help them with one of the most important transitions of their lives in many cases. I am incredibly grateful for that trust and support because it’s helped me continue to grow and thrive in an industry that often tests your tenacity and resilience,” said Stallworth. Emily Bowler, Executive Director of the IBBA, congratulated this year's award recipients. "The professionals recognized through the IBBA's Member Excellence Awards program represent the highest standards of our profession. Their dedication, expertise, and commitment to helping business owners successfully transition their businesses have a lasting impact on entrepreneurs, employees, families, and communities. We are proud to recognize Terri Stallworth for this outstanding achievement and her contributions to the business brokerage industry." Award recipients are recognized based on verified business transactions completed during the previous calendar year. The IBBA's Member Excellence Awards program celebrates the accomplishments of professionals who demonstrate excellence in business brokerage and mergers and acquisitions advisory services. For more information about Terri Stallworth and Terri Sherman Stallworth, PA or Florida Business Exchange, Inc., visit www.MindYourBusinessToday.com or contact Terri@MindYourBusinessToday.com. About Terri Sherman Stallworth, PA Terri Stallworth has been with Florida Business Exchange, Inc. since 2011 as a Business Intermediary operating under Terri Sherman Stallworth, PA (formerly Terri D. Sherman, PA). She is a member of the Business Brokers of Florida (BBF) and International Business Brokers Association (IBBA), through whom she is designated a Certified Business Intermediary (CBI). She specializes in the sales of main street businesses and has sold a host of businesses across the state of Florida. Terri has been the recipient of the BBF’s “Million Dollar Plus” & “Dealmaker” awards, and the IBBA’s “Outstanding Producer” & “Chairman’s Circle” awards. She is ready to help you “mind your business today”! About Florida Business Exchange, Inc. Florida Business Exchange (FBX) has been serving buyers and sellers in the state of Florida since 1990. Founded by the current Broker/Owner, Bert Risdon, the company was one of the few business brokers in the state and established its first office in the Orlando, Florida area. In the early 2000’s, FBX began to expand and opened offices in Tampa Bay and Jacksonville. In 2016, FBX established a corporate headquarters in Volusia County, Florida and began to actively recruit new associates for the various offices around the state. As of today, FBX is one of the largest non-franchised business brokerage firms in Florida and has sold over 1500 businesses worth over 500 million of dollars. About the International Business Brokers Association (IBBA) Founded in 1984 and with more than 3,000 members worldwide, the International Business Brokers Association (IBBA) is the largest international non-profit association operating exclusively for people and firms engaged in business brokerage and mergers and acquisitions. The IBBA provides education, conferences, professional designations, networking opportunities, and resources to support the business brokerage profession and the successful transfer of business ownership. For more information, visit www.ibba.org . 
by Terri Stallworth • 15 May 2026
A lot of sellers are surprised to learn that their business itself has to qualify for an SBA loan, separately from the buyer. SBA 7(a) acquisition financing isn't like a home mortgage, where the bank evaluates the borrower and the property is mostly collateral. The lender is essentially underwriting two borrowers at once: the human buyer (credit, experience, liquidity, post-close working capital) and the business itself (cash flow, add-back legitimacy, industry risk, customer concentration). If either side fails underwriting, the deal doesn't fund. That's why a seller can have a perfectly qualified buyer sitting at the table and still watch the deal fall apart, not because the buyer was the problem, but because the business couldn't carry the proposed debt at the agreed price. Sellers often experience this as "the buyer's loan fell through," when the real issue was on their side of the table. Frequent reasons businesses don't qualify for an SBA 7(a) loan: 1.The business cash flow genuinely doesn’t support the debt at the asking price: This comes down to a metric called the Debt Service Coverage Ratio (DSCR). Lenders want to see the business producing at least 1.25x the debt payments the buyer would take on at closing. 2. Cash flow exists on paper but can't be substantiated: We often call this “owner to prove” financials. Though they may be real numbers that can be proven through bank statements, POS reports, or similar means, if it can't be documented and proven through financial statements and tax returns, it can't be counted from the lender’s perspective. 3. Add-backs are too aggressive: You may have heard some say, “I write everything off through my business!” Well, that may be so. However, not all of those discretionary expenses are valid add-backs from the lender’s view, and the lender won't credit them. So the cashflow is reduced because those “write-offs” stay in the expenses. 4. Something structural about the business is amiss: A heavy customer concentration, deep owner dependence, or a difficult industry are just a few examples of issues that make the lender hesitant regardless of the gross revenue and/or profit. An honest word about add-backs: There's a common belief that lenders are unpredictable and will slash add-backs to ribbons. The truth is closer to the opposite. Lenders are conservative and predictable. When add-backs are recast the way a lender will actually evaluate them—defensibly, not aspirationally—somewhere in the range of 90–95% of them survive review. The breakdowns happen when the recast was inflated to puff up the headline number, not because lenders are out to get anyone. A role of a good business intermediary is to help best position you to successfully get through underwriting, and that often starts with the recast financials. The knowledge gap that surprises most sellers: Buyers often understand DSCR better than sellers do. That may sound backwards… you'd expect the seller, who's run the business for years, to know the cash flow inside and out. Yet, buyers learn this material because they have to. They sit across from an SBA lender and get the education whether they want it or not. Most sellers have never had that conversation. As you begin thinking about a business exit, especially through a sale, ask the business intermediary you’re working with what you need to know about DSCR that you may not know. What this means for you: If selling is on your radar, even if it's a year or two out, running the DSCR math early is one of the most valuable exercises you can do. It tells you whether your asking price is supportable by financing, where your add-back stack might be exposed, and what (if anything) needs to be tightened up before going to market. When the price is right and the numbers hold up, deals close. When they don't, you tend to learn it the hard way, usually after weeks of momentum and one disappointing call from the buyer's lender. Bottom line: clean books, defensible add-backs, and a price that pencils to a real DSCR aren't merely nice-to-haves. They're the foundation every successful sale is built on ! A note about businesses that won’t work for SBA financing: When a business won't qualify for SBA financing at the desired price, or at all, it doesn’t mean the business isn’t viable. It just means it isn’t viable for SBA financing. There are still paths to a deal, most often through seller participation (a seller note covering some of the gap) or through a strategic buyer who isn't relying on third-party financing. These structures aren't a fallback so much as a tool, and they're worth understanding well before they're needed.
by Terri Stallworth • 22 May 2025
Deciding to buy a business is a major step, but how do you know where to start? What should you have prepared? How do you find the businesses for sale? Here are the top 5 tips I think every buyer should read before beginning a search for the right opportunity. 1. CREATE YOUR SEARCH CRITERIA Think about your strengths and weaknesses, and decide what attributes of an opportunity matter most to you. Do you have any specialized skills that you think you can add to a business—marketing, technical, sales, managerial, etc.? Are there any skills or elements that you feel need to already be in place with the business? What kind of return on your investment are you hoping for? What is the minimum net profit you require? Beginning to think and ask yourself questions along these lines will help you figure out what types of opportunities best fit you and your goals so that you can be specific in your search. It will also help you search with an end in mind—making a purchase! 2. KNOW YOUR (PERSONAL) NUMBERS Consider your available capital and know your (personal) numbers. Ask yourself—How much of your own personal capital to do you have readily available to leverage for a down payment? How much, if any, additional capital do you need and what are your options? The SBA is great, but not all businesses and/or buyers qualify for SBA funding. Perhaps seller financing is a better option for what you are trying to accomplish. Either way, have a solid idea of what you have readily available before you start to search. This will also help you be narrow your search options. Also, remember that you have to factor in the other associated costs that you will incur with a business transfer—deposits, insurance, licenses, etc. You should consider those associated costs as expenses that will be deducted from your personal capital, as most of them need to be paid before closing. By creating a projected budget of these associated costs before you search, you will not be caught off guard as you approach the finish line—the closing table. 3. WORK WITH A PROFESSIONAL As you begin to search for opportunities, work with a professional. This will make the transfer process a lot smoother, and he or she will help match you to opportunities that fit your criteria. When seeking out a business broker or business intermediary, ask them what professional organizations they belong to. You also want to ask if business sales are their specialization. Make sure you are working with someone whose expertise is in business sales because he or she is going to know and understand all of the various moving parts that function as part of a business transfer. * Bonus tip: you want to make sure you work with someone who takes the time to help you understand the process. You certainly should respect the person’s time and be reasonable in your expectations, but he or she should never make you feel as though they do not have time to answer your questions or address your concerns. 4. SIGN AN NDA AND PROVIDE A PERSONAL FINANCIAL STATEMENT Be prepared to sign a non-disclosure agreement (NDA) and provide a personal financial statement (PFS) BEFORE you are given any details or proprietary info to review on a business opportunity. If you really want to stand out from other prospective buyers, also provide a resume or executive summary along with your executed NDA and PFS. This shows the business broker or business intermediary that you are serious. Also, respect the confidentiality of the Seller and the opportunity—it helps protect the seller and you as the buyer because it ultimately protects the goodwill of the business. 5. REMEMBER THAT THERE’S NO SUCH THING AS A PERFECT BUSINESS Remember that there’s no such thing as a perfect business! The reason you buy an existing business is to grow and improve on what is already in place. Once you find an opportunity that checks all of your boxes, make an offer. Though the business acquisition process has a lot of moving parts, it does not have to be overwhelming. By preparing yourself before you start to find businesses to purchase, and by working with the right business broker and/or business intermediary, you will certainly strengthen your chance of becoming the business owner you always dreamed of being! To explore businesses for sale in Florida, click here . If you are looking for a Certified Business Intermediary to work with to help you find the right opportunity in Florida, contact Terri Sherman Stallworth, P.A., Certified Business Intermediary with Florida Business Exchange, Inc. (Broker) at 888.925.5055 x 207 and let Terri help you “mind your business today”!
by Florida Business Exchange | Proud Sponsor of the 2025 Small Business Success Summit • 22 May 2025
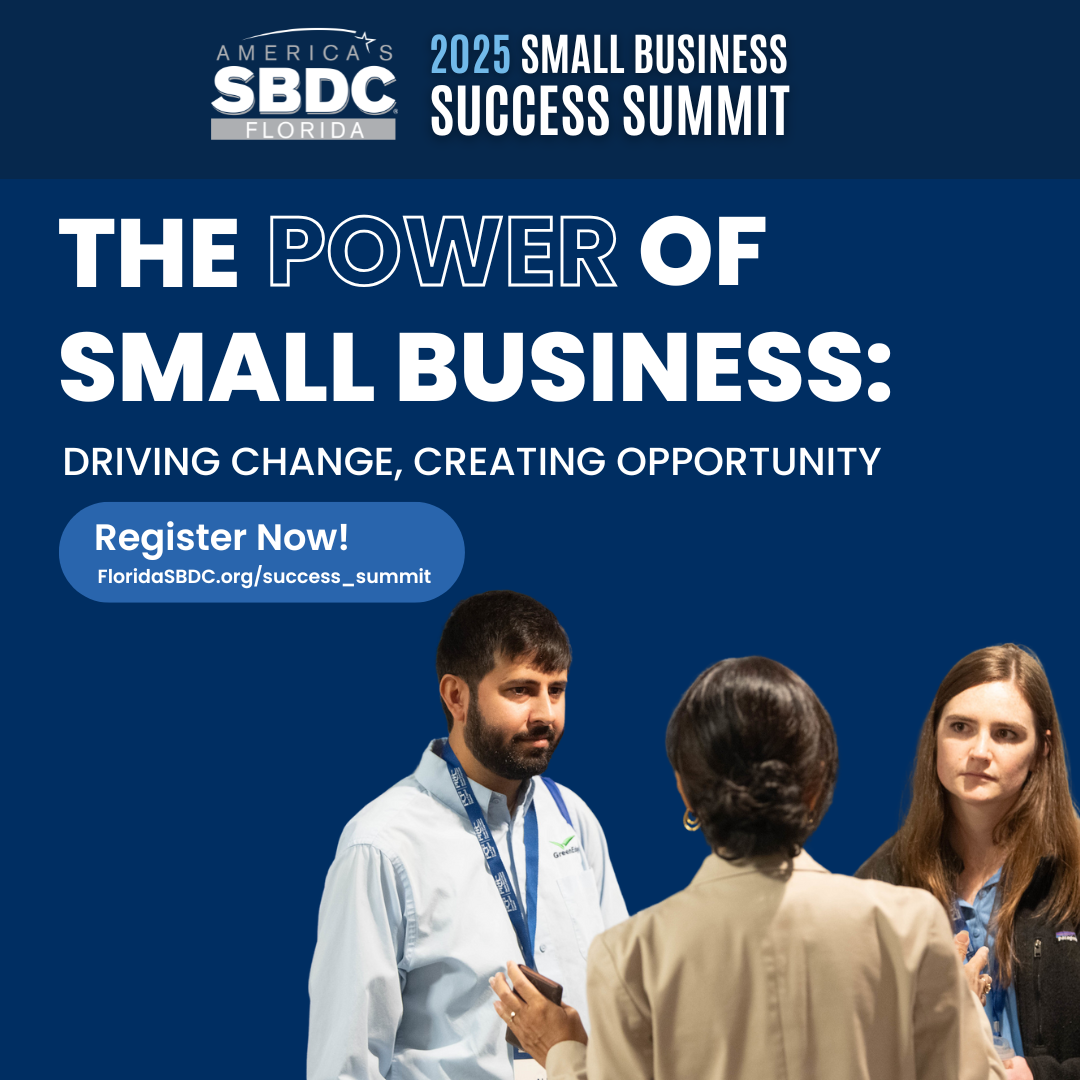
Running a small business can feel isolating at times, but you’re not alone. That's why the Florida Business Exchange believes so strongly in the power of connection and community through events like the 2025 Small Business Success Summit . This annual event, hosted by the Florida SBDC Network, is more than just a conference. It’s a space where entrepreneurs come together to learn, connect, and grow. And as a proud sponsor, we want to share why events like this are so valuable to Florida’s business community. Why this matters: Professional development is essential for staying competitive and thriving in today’s fast-changing business environment. Whether it’s learning a new skill, gaining fresh insights, drawing inspiration, or building a network of like-minded individuals, the time you spend on professional growth directly impacts your business’s success. Here’s what you can expect from attending the Small Business Success Summit: ● Connect with like-minded entrepreneurs who share your challenges and ambitions ● Discover new opportunities, partners, and resources that can help you grow ● Exchange insights and best practices with fellow business owners ● Learn from inspiring leaders and industry experts who offer actionable advice ● Build relationships that can lead to mentorship, collaboration, or investment Let’s Connect No small business succeeds in isolation. Building relationships with other business owners, mentors, and experts can inspire new ideas, spark collaboration, and even open new doors. If you’re ready to invest in yourself and your business, we hope you’ll join us.The 2025 Small Business Success Summit will be held August 18-19 in Tampa at the Grand Hyatt Tampa Bay . Learn more about this year’s event and register at https://floridasbdc.org/success_summit/ .